
Global Overview
Markets continue to advance, but the tone has shifted from enthusiastic to selective. Equity indices in the United States and parts of Europe remain near recent highs, while emerging markets show mixed momentum.
The central drivers remain unchanged:
- Earnings: Slowing from the sharp rebound phase but still positive.
- Inflation: Gradually moderating, though not uniformly across regions.
- Interest Rates: Largely stable, with central banks signalling patience rather than urgency.
As I often remind readers, stock prices are driven by earnings, inflation, and interest rates. When earnings are resilient and inflation is contained, markets tend to find support — even if progress becomes uneven.
This is not a time for prediction. It is a time for orientation.
South Africa
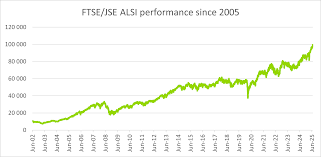
FTSE/JSE All Share Index

Market Performance
The JSE All Share closed the week marginally higher, though gains were concentrated in resource counters. Industrials were more subdued, reflecting slower domestic momentum.
Earnings
Forward earnings estimates for the broader market remain modestly positive. Resource companies continue to benefit from commodity stabilisation, while consumer-facing businesses show mixed performance.
Earnings trend: Improving modestly, but uneven.
Inflation & Interest Rates
South African inflation continues to trend lower compared to last year’s levels, though progress has slowed.
The South African Reserve Bank has maintained a cautious stance, keeping policy rates steady while signalling that inflation risks remain.
Inflation: Gradually easing.
Interest Rates: Stable at restrictive levels.
Domestic Context
Electricity constraints and structural growth challenges remain. However, the equity market appears to be discounting gradual stabilisation rather than deterioration.
United States
S&P 500
4
Market Performance
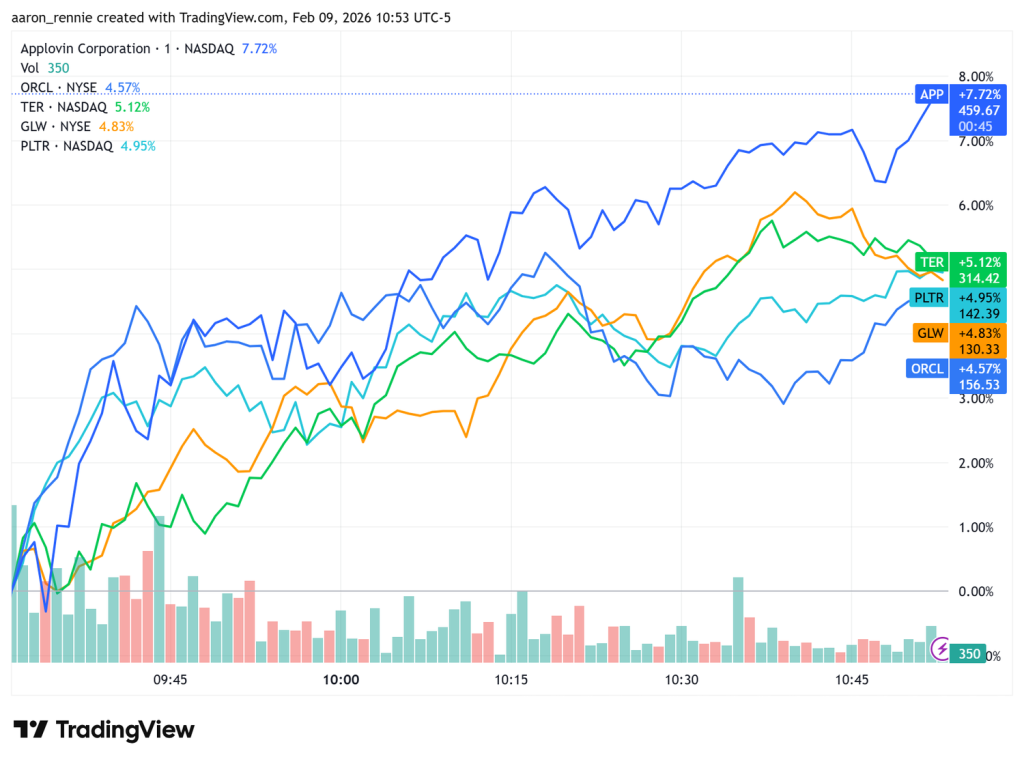
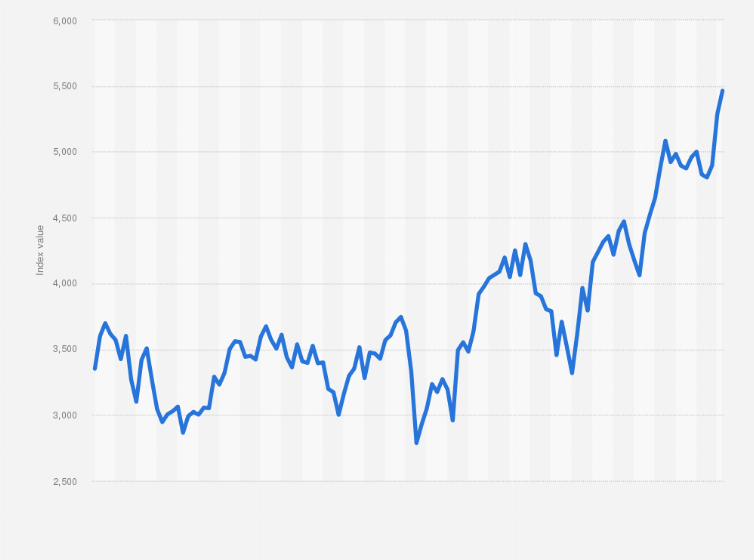
The S&P 500 finished the week slightly higher but with noticeable rotation beneath the surface. Leadership remains concentrated in high-quality growth and technology names, while smaller capitalisation shares lag.
Earnings
Fourth-quarter reporting season is nearing completion. Results have generally exceeded lowered expectations, though forward guidance has become more conservative.
Earnings trend: Positive but decelerating.
Inflation
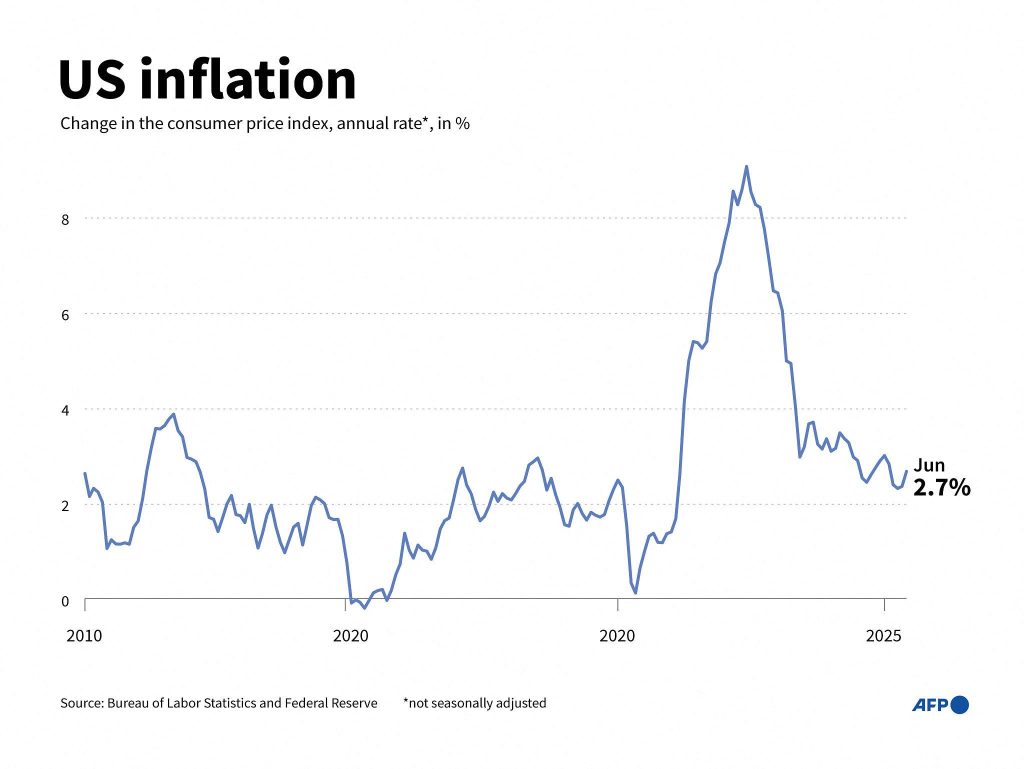
Latest CPI data show inflation continuing to moderate year-on-year, though services inflation remains sticky.
Inflation: Falling gradually, but not yet at target.
Federal Reserve & Rates
The Federal Reserve continues to signal patience. Markets expect eventual easing later in the year, but officials remain focused on ensuring inflation is durably contained.
US 10-year Treasury yields moved slightly higher this week, reflecting some repricing of rate expectations.
Interest Rates: Stable policy stance; bond yields mildly higher.
Labour Market
Employment conditions remain resilient, though hiring momentum has slowed from last year’s pace.
Global Markets
Europe
4
The Euro Stoxx 50 continues to recover gradually. Inflation in the eurozone is easing, allowing the European Central Bank to maintain a steady policy posture.
Earnings: Improving slowly.
Inflation: Falling.
Interest Rates: Stable.
China
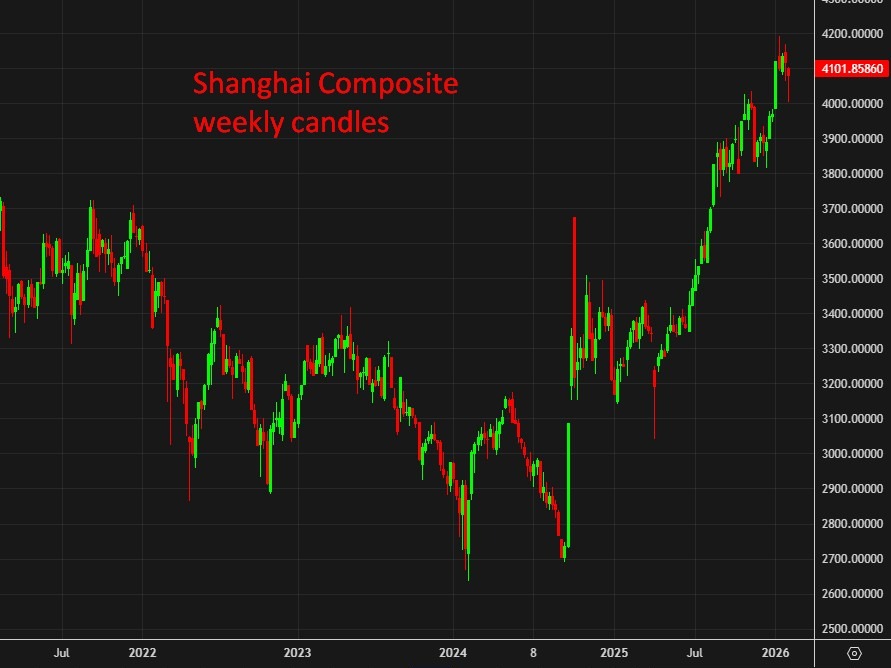
The Shanghai Composite Index remains volatile. Policy support measures are being introduced incrementally, but investor confidence remains fragile.
Earnings: Weak but stabilising.
Inflation: Low.
Interest Rates: Accommodative.
Emerging Markets
The MSCI Emerging Markets Index is mixed. Commodity exporters are benefiting from stabilising prices, while others struggle with currency volatility.
Strategic Perspective
In Stocks, Strategies & Common Sense, I emphasise that earnings growth is the engine that drives share prices .
At present, the global environment reflects:
- Slowing but positive earnings growth
- Moderating inflation
- Stable, still-elevated interest rates
This combination typically produces steady but selective markets rather than explosive advances.
It is important to remember that markets often turn when emotions are most extreme. We are not seeing extremes. We are seeing moderation.
Successful investors do not react to headlines. They respond to evidence.
Market Weather Summary
1. Seasonal Backdrop (Monthly Anchor)
Market Season: Late Spring
Season Status: Holding
The broader environment continues to reflect expanding earnings with stabilising inflation. However, momentum is no longer accelerating. The season is intact, but not strengthening.
2. Weekly Market Weather
This Week: Mostly Calm
Markets advanced modestly with selective volatility beneath the surface. Leadership remains narrow, and risk appetite is present but controlled.
3. Interpretation
This week’s data reinforce the existing Late Spring backdrop. Earnings resilience continues to offset macro uncertainty, while inflation moderation allows central banks to remain patient.
Conditions support progress — but at a measured pace. The weather suggests forward movement with pauses, not acceleration.
4. Investor Orientation
In this environment:
- Patience is more valuable than prediction.
- Selectivity matters more than activity.
- Risk control remains essential.
There is no need for aggressive repositioning based on short-term noise.
As I have often written, doing nothing is sometimes the most difficult — and most profitable — action an investor can take.
Remain disciplined. Let earnings lead. Let inflation confirm. Let interest rates stabilise.
And above all, keep your emotions aligned with your plan.
Data and indications referenced are based on current market sources and macroeconomic reports available as of the week ending 14 February 2026.
Steady Progress, Selective Strength — Markets Hold Their Late Spring Tone
Earnings Resilience Offsets Moderating Inflation as Interest Rates Remain Steady