
Global Overview
Global equity markets closed the week in a generally constructive tone, but with less enthusiasm than earlier in the quarter. Earnings expectations remain positive across major developed markets, inflation continues to moderate in most regions, and interest rates appear stable at elevated levels.
The key message remains unchanged: earnings are the primary driver of stock prices, but inflation and interest rates determine the multiple investors are willing to pay for those earnings. At present, earnings resilience is offsetting macro uncertainty, but the environment is no longer accelerating — it is progressing with pauses.
South Africa
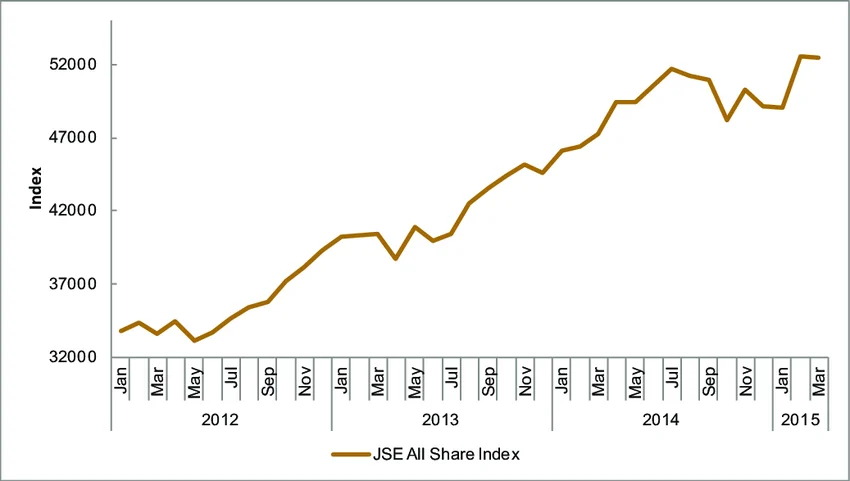
The Johannesburg Stock Exchange (JSE) All Share Index traded moderately higher this week, supported by firmer commodity prices and improved sentiment toward global cyclicals.
Earnings
Forward earnings expectations for the JSE All Share remain stable to slightly improving. Resource counters continue to benefit from steady global demand, while financials reflect stable credit conditions. Broadly speaking, earnings are holding firm.
Inflation & Interest Rates
South African inflation remains contained within the target band, though not decisively falling. The South African Reserve Bank has maintained a cautious stance, keeping policy rates steady while monitoring currency volatility.
Interest rates are therefore stable but elevated — not restrictive enough to derail earnings, but not stimulative either.
Domestic Developments
Load-shedding pressures have eased relative to prior years, and fiscal rhetoric remains disciplined. That said, growth remains modest.
Assessment:
- Earnings: Improving modestly
- Inflation: Gradually moderating
- Interest Rates: Stable
This combination remains supportive for equities, provided global conditions do not deteriorate.
United States

4
The S&P 500 finished the week modestly higher, though leadership narrowed. Technology and select growth names continue to carry a disproportionate share of index performance.
Earnings
Forward 12-month EPS estimates remain positive, though the pace of upward revisions has slowed. Corporate profitability remains strong, especially in technology and industrial automation.
Earnings are still expanding, but at a more measured pace.
Inflation
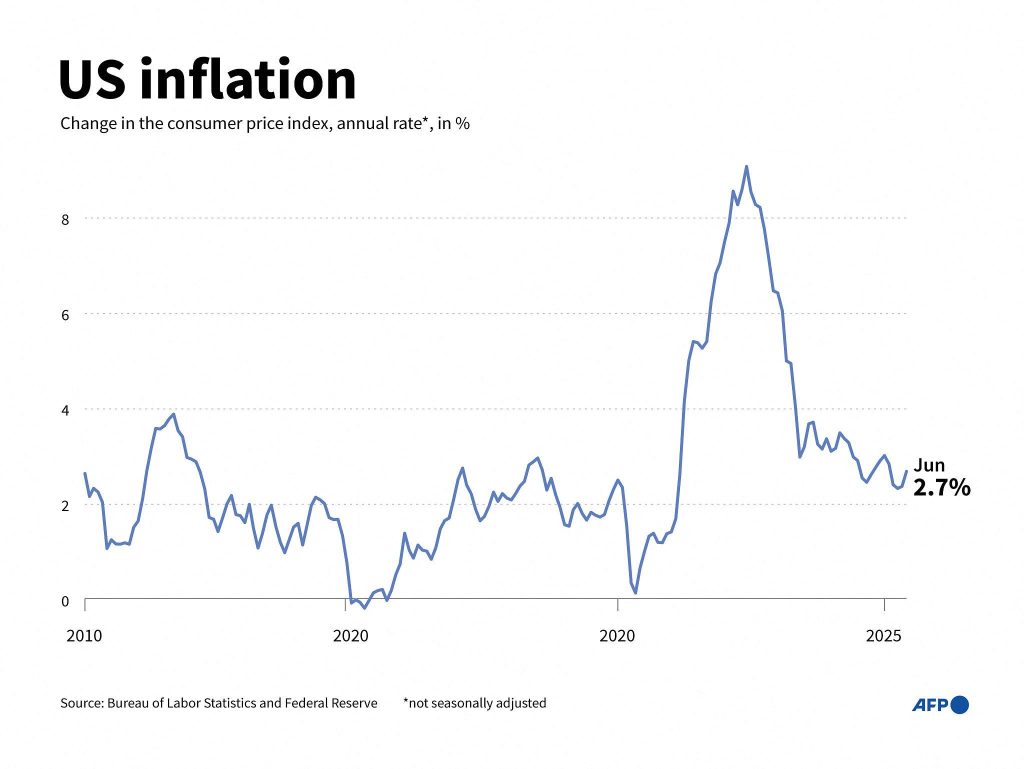
Recent CPI readings show continued moderation from prior peaks, though progress toward the 2% target remains gradual. Services inflation remains sticky.
Federal Reserve & Rates
The Federal Reserve has maintained policy rates at restrictive levels. Bond yields have stabilized but remain elevated relative to pre-2022 norms.
The labor market remains firm, though job growth has cooled modestly — a sign of normalization rather than contraction.
Assessment:
- Earnings: Expanding
- Inflation: Falling gradually
- Interest Rates: Stable at restrictive levels
This remains a constructive but mature phase of the cycle. Valuations require continued earnings delivery to justify current levels.
Global Markets

4
Europe
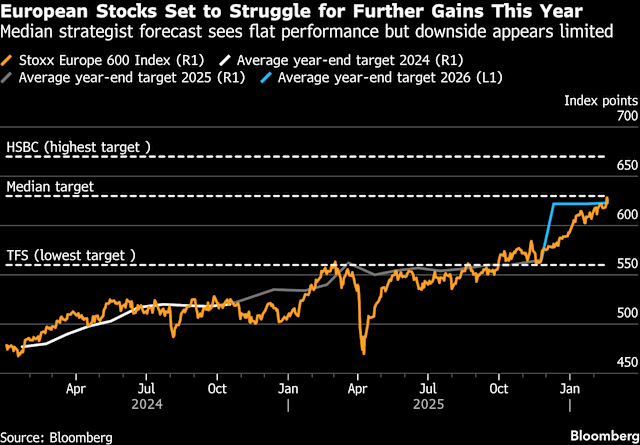
European markets have stabilized. The European Central Bank maintains cautious guidance as inflation moderates unevenly. Earnings growth remains modest but positive.
China
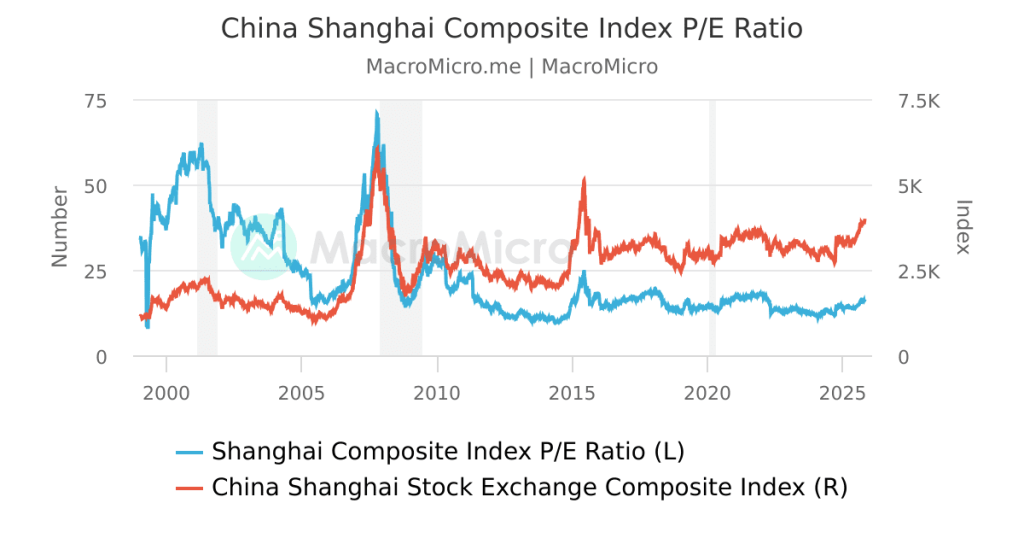
The Shanghai Composite Index remains range-bound. Stimulus measures continue, but structural growth challenges persist. Earnings stabilization is evident, but acceleration is not yet visible.
Emerging Markets
The MSCI Emerging Markets Index reflects mixed performance, heavily influenced by currency stability and commodity exposure.
Global Assessment:
- Earnings: Improving but uneven
- Inflation: Moderating
- Interest Rates: Mostly stable
Capital Seasons – Market Weather Layer
“This week’s Capital Seasons Weather Map registers Late Spring, with Mostly Calm conditions and a Holding posture.”
Trend Assessment
The structure remains constructive. Momentum is steady, though no longer accelerating. The trend engine suggests ongoing support rather than fresh ignition.
Participation & Rotation
Leadership has narrowed modestly. Participation remains positive but less broad than earlier in the quarter.
Volatility & Stress
Volatility is slightly elevated compared to recent weeks but remains contained. Stress conditions suggest awareness, not fear.
Liquidity Backdrop
The dollar remains firm, implying neutral to slightly tightening financial conditions. Liquidity is not expanding aggressively, but neither is it contracting sharply.
Tactical Discipline Close
In this environment, discipline takes priority over aggression. Maintain balance. Allow earnings to do the heavy lifting.
Website Weather Commentary
Season: Late Spring
Weekly Signal: Mostly Calm
Posture: Holding
Markets continue to reflect a supportive but measured tone. Earnings resilience offsets macro uncertainty, while participation narrows modestly. Volatility remains contained. Conditions suggest steady progress rather than acceleration.
Data and indications referenced are based on current market sources and macroeconomic reports available as of the week ending 20 February 2026.
Progress with Pauses: Earnings Continue to Lead
Resilient corporate profits offset macro uncertainty in a mature expansion.