
Global Overview

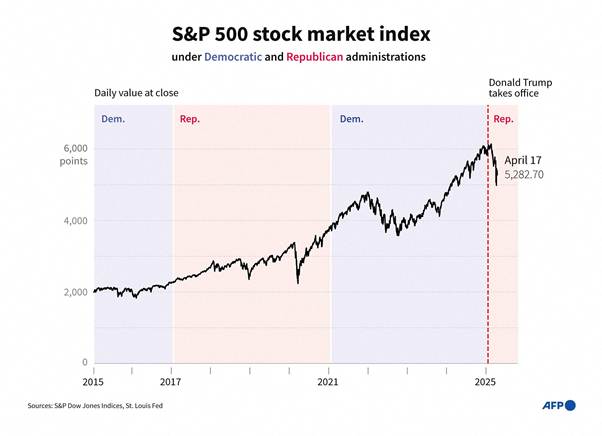
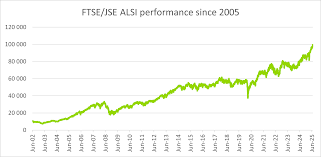
As we close the first full trading week of February, the global investment landscape remains shaped by the same three forces that always matter most: earnings, inflation, and interest rates. Markets continue to oscillate as investors weigh reasonably resilient earnings against the reality that inflation has proven slower to retreat than many had hoped, keeping central banks cautious rather than accommodative.
Equity markets are not behaving irrationally. They are doing what markets do when fundamentals are mixed: advancing in fits and starts, rewarding selectivity, and punishing excess optimism.
South Africa
JSE Performance
The JSE All Share Index ended the week modestly higher, supported by strength in selected resource and rand-hedge shares, while domestic-facing sectors remained uneven.
This is not a runaway market. It is a market that is working, not celebrating.
Earnings Trends
Aggregate earnings expectations for the JSE continue to edge higher, albeit slowly. Exporters and global earners remain the primary contributors to growth, while purely domestic companies are still contending with constrained consumer demand and rising input costs.
Earnings are improving, but not accelerating.
Inflation and Interest Rates
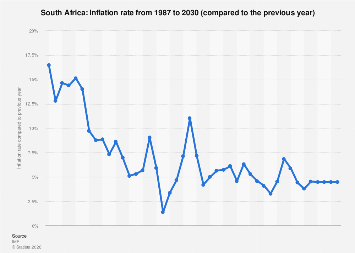
South African inflation has continued to cool gradually, remaining within the upper half of the SARB’s target range. Progress is real, but it is not yet decisive.
The South African Reserve Bank held its policy rate steady again this week, reinforcing its message: rate cuts will only come once inflation moderation is clearly entrenched.
Interest rates are stable, but not yet supportive.
Domestic Economic Context
Economic data continue to reflect slow but uneven improvement. Structural constraints remain, but modest gains in electricity stability and logistics are helping prevent further deterioration.
United States

Market Performance
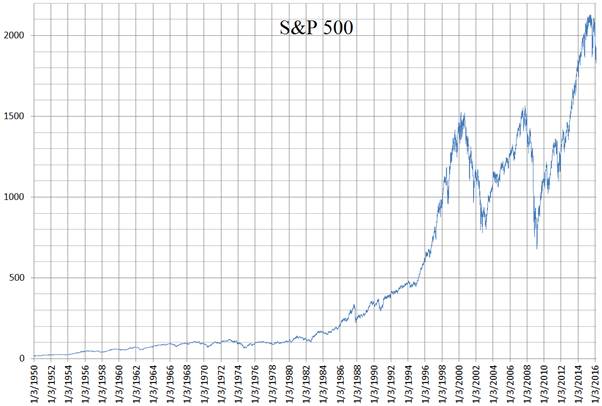
The S&P 500 finished the week little changed, after intraweek volatility driven by earnings releases and renewed debate about the timing of future rate cuts.
This remains a selective market, not a broad-based surge.
Earnings Trends
US earnings expectations for 2026 continue to improve modestly, led by technology, communication services, and select industrials. Importantly, earnings revisions have been more positive than negative—an essential condition for sustained market progress.
Earnings are improving, but at a measured pace.
Inflation and Federal Reserve Policy
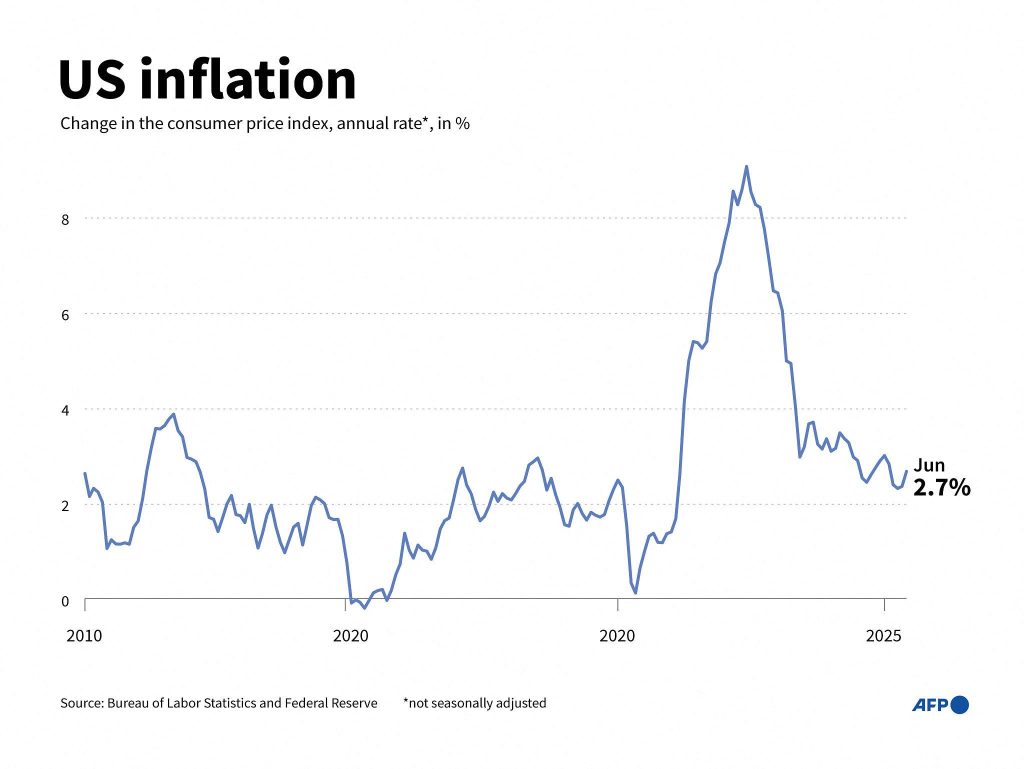
Recent CPI data confirm that inflation is falling, but slowly. Services inflation, in particular, remains sticky.
The Federal Reserve left policy unchanged and reiterated that it requires confidence, not hope, before easing. Markets are gradually adjusting to a “higher-for-longer” reality.
Interest rates are stable, with a downward bias still conditional.
Labour Market
The US labour market remains firm, though no longer overheating. This balance supports consumption but also explains the Fed’s patience.
Global Markets
Global Markets
Europe
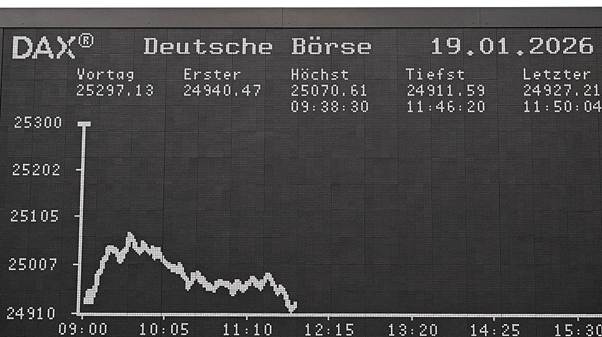
European equities were mixed as slowing inflation offered relief, but weak growth data limited enthusiasm. Earnings expectations remain subdued, particularly in manufacturing-heavy economies.
China
Chinese markets remain fragile. Policy support is increasing incrementally, but investor confidence is not yet restored. Earnings visibility remains poor, and caution remains warranted.
Emerging Markets
Emerging markets are benefitting selectively from stable US rates and a contained dollar, but outcomes vary widely by country and policy discipline.
Market Weather Summary
1. Seasonal Backdrop (Monthly Anchor)
Season: Late Spring
Status: Holding
The earnings backdrop continues to support the broader advance, but inflation and interest rates are preventing acceleration.
2. Weekly Market Weather
Conditions: Mostly calm, with mixed undercurrents
Short-term volatility surfaced during the week, but without signs of systemic stress.
3. Interpretation (Plain Language)
This week fits comfortably within the current season. Earnings resilience continues to offset macro uncertainty, but not strongly enough to produce a clear breakout. The environment remains constructive, yet demanding of patience.
4. Investor Orientation (Guidance)
This is a time for selectivity rather than speed, process rather than prediction, and discipline rather than reaction. Investors are best served by staying aligned with long-term fundamentals and resisting the urge to act simply to relieve discomfort.
Markets will always test resolve before they reward it. Those who remain calm, informed, and disciplined are rarely the ones who need luck.
Data and indications referenced are based on current market sources and macroeconomic reports available as of the week ending 6 February 2026.
Holding the Line: Earnings Improve, Patience Required
Progress Is Real — Acceleration Is Not