
Global Overview
Global equity markets continue to reflect a constructive, though maturing, expansion phase. Corporate earnings across major developed markets remain positive on a year-over-year basis, but the rate of acceleration is moderating. Inflation trends remain contained relative to 2022–2023 peaks, though services inflation in several regions remains sticky. Central banks, broadly speaking, are no longer tightening aggressively, but they are also not in a hurry to ease decisively.
As always, we return to first principles:
Earnings drive stock prices. Inflation influences interest rates. Interest rates influence valuations.
The interplay of these three forces remains moderately supportive of equities — but without the powerful tailwinds seen during early-cycle recoveries.
South Africa
Market Performance
FTSE/JSE All Share Index
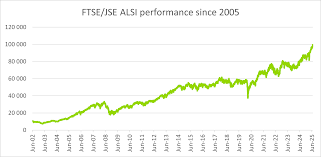
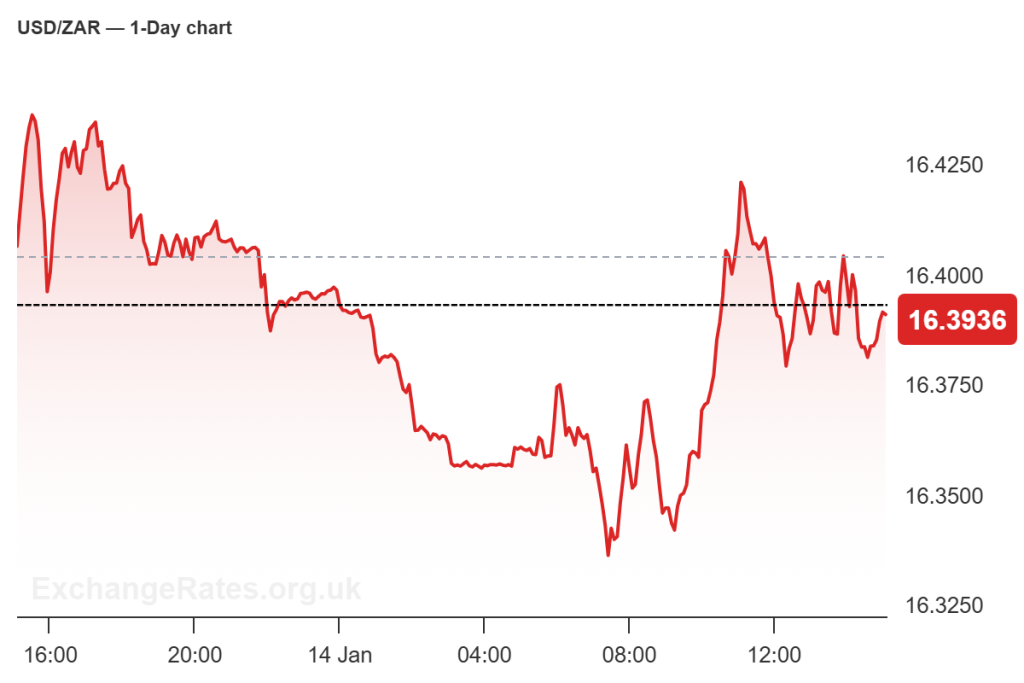
The JSE All Share traded with moderate upward bias this week, supported by resource counters and selected industrials. Financials remain sensitive to bond yield movements and currency stability.
Earnings
Forward earnings expectations for major JSE constituents remain stable to modestly improving. Resource sector earnings are stabilizing after prior volatility, while domestic-focused companies show gradual recovery as load-shedding disruptions ease marginally.
Assessment: Earnings are improving modestly, but not accelerating sharply.
Inflation & Interest Rates
South African inflation remains within the SARB’s target band, though near the upper range. The South African Reserve Bank has maintained a cautious stance, keeping rates steady while signaling data dependency.
Bond yields remain elevated relative to pre-2022 levels but stable.
Assessment:
- Inflation: Moderating but sticky
- Interest rates: Stable at restrictive levels
Domestic Backdrop
Structural challenges persist — energy reliability, logistics constraints, and fiscal pressures. However, corporate South Africa continues to demonstrate resilience.
United States
Market Performance
S&P 500

The S&P 500 remains near recent highs, though breadth has narrowed somewhat. Leadership is concentrated in large-cap growth and select technology sectors.
Earnings
Forward 12-month EPS expectations remain positive. Growth has slowed from last year’s pace but remains constructive. Profit margins are holding up better than many anticipated.
Assessment: Earnings are rising, but at a slower rate.
Inflation & Federal Reserve Policy
Recent CPI data show continued moderation in headline inflation, though core services remain firm.
The Federal Reserve maintains a patient posture. Rate cuts are anticipated later in the year, but policy remains restrictive for now.
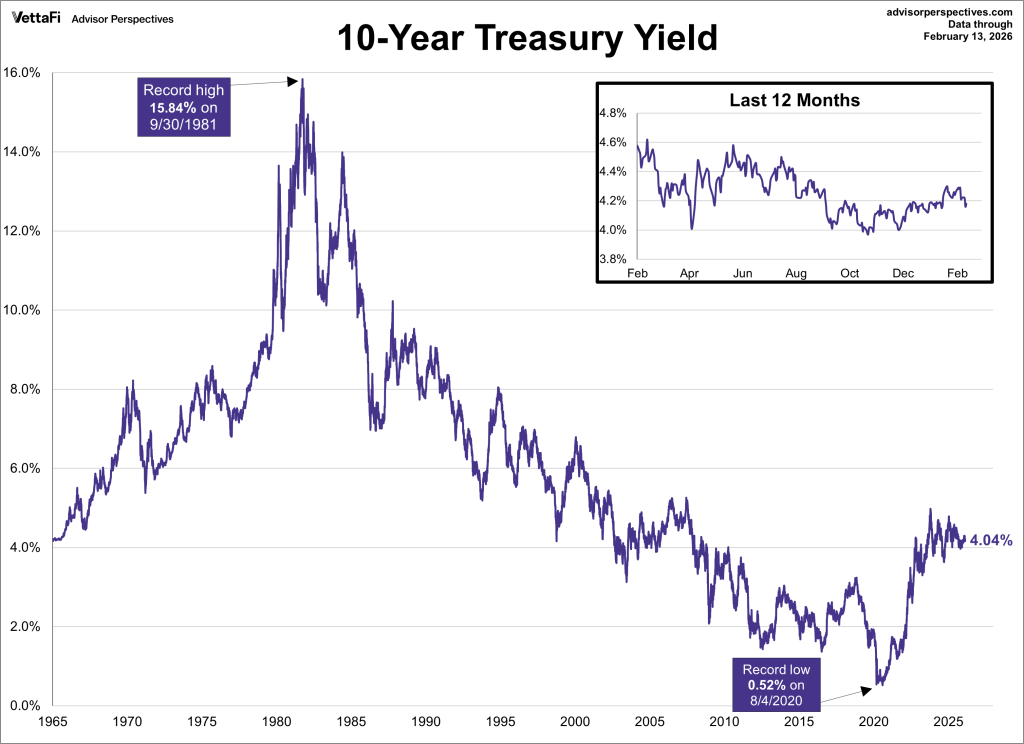
US 10-year yields remain range-bound.
Assessment:
- Inflation: Gradually declining
- Interest rates: Stable but restrictive
Labour Market
Employment remains resilient. Wage growth is moderating but not collapsing — consistent with a late-expansion environment.
Global Markets
Europe
STOXX Europe 600
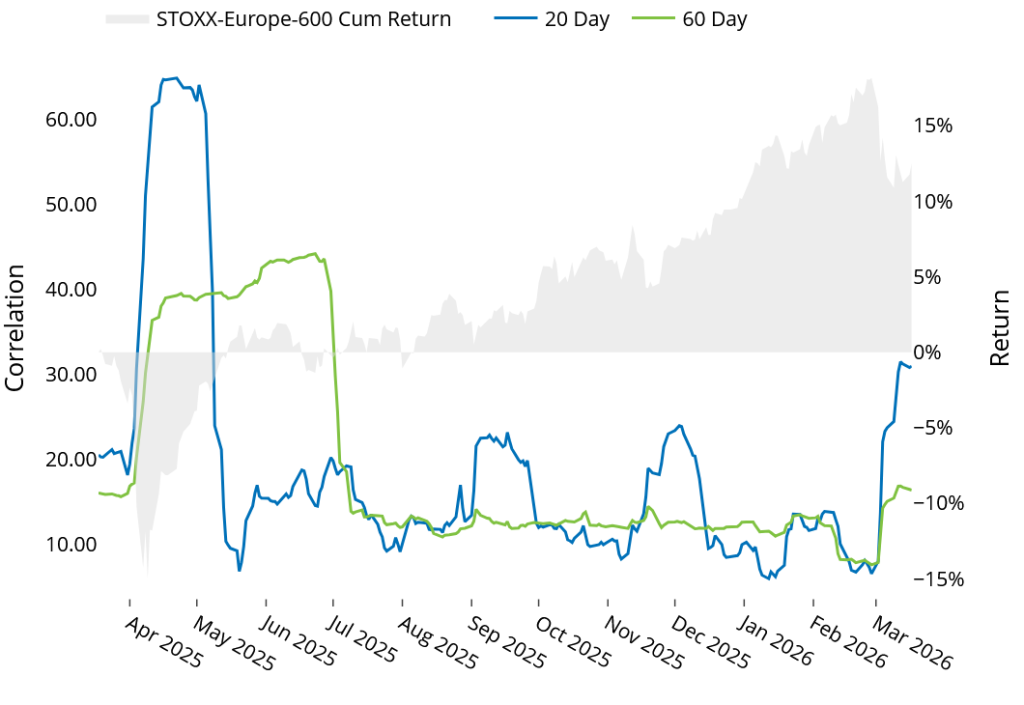

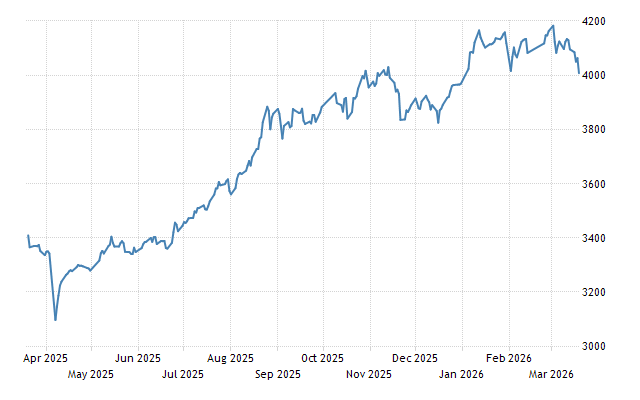
European equities are steady. Inflation continues to ease gradually, giving the European Central Bank room for cautious flexibility later in the year.
Earnings growth is modest but positive.
China
Shanghai Composite Index
Chinese markets remain volatile. Policy stimulus measures continue, but investor confidence remains fragile due to property sector adjustments.
Earnings visibility is less certain than in developed markets.
Emerging Markets
Emerging markets overall are benefiting from a stable US dollar and moderating global inflation. However, growth dispersion remains significant.
Strategy Guidance
In this environment:
- Favor companies with visible earnings growth
- Avoid speculative narratives unsupported by profits
- Maintain disciplined position sizing
- Respect market direction, but do not overreact to noise
Remember:
The objective is not to predict.
The objective is to align with earnings trends while managing risk.
Patience and discipline remain the investor’s greatest advantages.
Capital Seasons – Market Weather summary
1️⃣ Opening Declaration
This week’s Capital Seasons Weather Map registers Late Spring, with Mostly Calm conditions and a Holding posture.
2️⃣ Trend Assessment
Trend conditions remain constructive. The structure of the market is supportive, though momentum has flattened relative to earlier advances. This reflects stabilization rather than deterioration.
3️⃣ Participation & Rotation
Participation is somewhat narrower than earlier phases. Leadership is concentrated in quality earnings franchises. This is typical of a maturing expansion.
4️⃣ Volatility & Stress
Volatility is contained, though slightly elevated compared to recent weeks. There is caution beneath the surface, but not systemic stress. Defensive assets show interest, but not urgency.
5️⃣ Liquidity Backdrop
Liquidity conditions are neutral. The US dollar remains stable, implying neither tightening shock nor broad liquidity surge.
6️⃣ Tactical Discipline Close
In this environment, discipline takes priority over aggression.
Stay aligned with earnings. Avoid emotional decision-making. Allow the data to guide you.
Data and indications referenced are based on current market sources and macroeconomic reports available as of the week ending 28 February 2026.
Constructive Conditions Persist in a Maturing Expansion
Positive earnings trends support equities while leadership narrows and policy remain restrictive